Meeting with Rob Pasick (Part 1)
Posted by Mark on March 13, 2020 at 06:54 | Last modified: May 4, 2020 14:26Upon recommendation from a friend, I met with Dr. Robert Pasick one year ago. I composed this post (never finished) to serve as personal notes of that session.
Rob is an executive coach. I’m not sure if my referral had friendly contact or business in mind, but Rob is all business and he made that quite clear.
Not that I should really expect anything less—and I don’t. If ever the end product is making money, then it would seem a willingness to pay for the service is in order. I discussed this in the second paragraph here.
I started by reciting my 60-second elevator pitch:
> After working several years as a staff pharmacist and pharmacy manager, I retired
> to start a securities trading business at the age of 36. This has been a journey
> without clients or co-workers that has required extensive self-study, intrinsic
> motivation, and outside-the-box thinking. I have since learned a great deal about
> the mechanics of trading and investing. I have succeeded at replacing a six-figure
> pharmacist salary by posting average annual returns in excess of 15% from 2007
> onward. Having risked my own hard-earned capital to learn the craft, I now seek
> to manage wealth for others.
I explained some of my road blocks. The main one is lack of a sales background (see fourth paragraph here). Another is the fact that I trade options, which the financial industry views as extremely risky (as discussed here). He later noted the lack of a network of wealthy individuals who say “here’s a few million for you to manage… we love you, Mark!” is another block for me.
I have recently felt the need to really “network my *ss off” to get this business going. I also consider networking to be a weakness since I am not practiced at it.
Rob did not understand my sense of loneliness, which I proceeded to clarify. I said I have been unsuccessful at finding other full-time, independent, retail traders like myself (not of retirement age, but that’s not as important provided they have sufficient interest and dedication to collaborate) who trade for a living. In the absence of an investment advisory, which is probably #1 on my list of desired next steps, I could potentially form a research team to build the automated backtester (see paragraph #8 here) and proceed with my extensive list of research topics. That could shape my future trading* and/or serve as a foundation for professionally managed accounts.
I will continue next time.
* — I have since become more interested in trading futures, as discussed in many posts since (e.g. here).
Categories: About Me | Comments (0) | PermalinkIn Need of Performance Update
Posted by Mark on March 10, 2020 at 09:05 | Last modified: January 12, 2022 09:15One of my blog projects for the year is to get more organized by converting drafts to completed posts.
With a bit more work, incomplete drafts can become completed posts. Entering this year, I had over 30 entries in the “drafts” folder—some in excess of 450 words, which is my usual target. Completing these long drafts is a major coup because for less than the time it takes me to finish one from scratch, I can easily generate two, three, or even four complete posts.
With regard to these drafts, I typically write something like:
> In the longshot case that someone out there could possibly benefit
> from any of this, what follows is this post from August 2018.
Some of the drafts are well thought out, but I honestly have no idea where they fit. Some are without reference links to guide me. Some (like this one) are excessively complex and hard for me to decipher. I have no excuse for the latter except poor writing, quite honestly. Because they are just drafts I’m looking to complete, I include them and leave the decryption to you.
What follows is especially “in case someone out there could possibly benefit” content. Although it reminds me that a performance update is overdue, I am not sure what six-year period is being described. Perhaps when I go back and calculate performance, I will be able to resolve what follows. This post is therefore a call to action as stated in the title.
—————————
Keep in mind that my performance during said six year window, as discussed last time, was disappointing. However, showing performance since I started trading full-time provides evidence that I have done well overall. I believe the approach I have used recently is more disciplined, systematic, and therefore better than what I did in the early years of 2010 – 2014.
Then again, my stated 2010 – 2014 performance is not exactly bad. The high standard deviation (SD) hurts but that SD is to the upside. Upside SD will not cause sleepless nights, which is why a separate statistic differentiates upside from downside variance (Sortino Ratio). My 2012 return in excess of 50% is a major contributor to the high SD, which leaves risk-adjusted return much to be desired. Realistically speaking, though, clients would never complain about that.
Also with regard to multiplicative versus additive, what shocked me was to see a 10% improvement on the RAR ratio amounting to only 79 basis points. The problem with RAR is that it is unitless. 79 basis points is not 79 basis points, either. From 10% to 10.79% is only a 7.9% improvement whereas from 5% to 5.79% is a 15.8% improvement. When thinking in terms of management fee and overall compounded returns, we think about the additive difference.
Categories: Accountability | Comments (0) | PermalinkEnamored with Day Trading? (Part 2)
Posted by Mark on March 5, 2020 at 10:32 | Last modified: May 4, 2020 12:11Today I will finish up the last post by getting into some actual data about day traders.
Chague et al. tracked 19,646 day traders from 2013 through 2015. This study received lots of buzz in Brazil. In addition to being extremely popular, day trading is also very controversial there.
The results boiled down as follows:
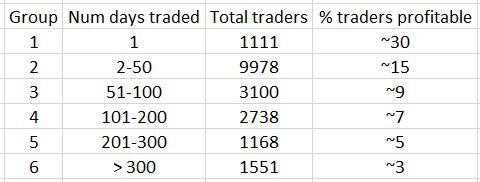
These data suggest day trading and casino roulette share similar odds of winning. The more people day trade, the better the chance they have to lose everything.
Chague et al. explain the results run contrary to self-selection. In self-selection, individuals with better performance generally persist in an activity. This is common in activities that exhibit “learning by doing.” Michael Mauboussin, in The Success Equation: Untangling Skill and Luck in Business, Sports, and Investing (2012), agrees: practice does not make perfect when the outcome is due to luck rather than skill.
Trading educators want us to believe something altogether different. I often see [day] trading advertised as a craft to be developed over time. I won’t be overnight sensation. It takes hard work. The more I practice, the more classes I take, the more mentoring sessions, the more I spend on this education, the more I will succeed. In the current study, empirical data along with statistical regression analysis showed performance to be deficient with those trading longer faring even worse.
Despite the poor averages, perhaps those who end up in the green are a smashing success. Looking at the 47 out of 1,551 day traders who were profitable after 300 days:
- Only 17 earned more than the Brazilian minimum wage (16 USD/day)
- Only eight earned more than an newbie Brazilian bank teller (54 USD/day)
- One earned 310 USD/day
For all the stress and strain of day trading, the chance of making a respectable $78,000/year was 0.06% and the chance of making more than an entry-level bank teller wage ($13,608) was 0.5%. No windfall profits were to be found with tiny profits few and far between. The average daily result was a loss of $49.
Even to realize the entry-level bank teller wage, one had to endure a large variability of returns. For the eight mentioned above, the daily profit ranged from $632 to $3308. In other words, that $54 average profit/day was usually between -$578 to +$686 per day for the most consistent and -$3254 to +$3362/day for the most volatile. Sleepless nights, anyone?
If the outlook isn’t bleak enough already, Chague et al. explain why their study is likely to overestimate actual performance. First, income taxes and other relevant expenses (e.g. trading platform cost, courses) were not included. Second, only days where total contracts bought equaled total contracts sold were included. They cite a study by Juhani Linnainmaa (University of California at Berkeley, 2005) that says retail day traders are reluctant to close losers (called the “disposition effect”). Days with unequal numbers of contracts bought versus sold were likely losers, therefore. By not including these in this study the abysmal reported day trading performance is, itself, artificially inflated.
Chague et al. conclude “it is virtually impossible for an individual to day trade for a living, contrary to what the brokerage specialists and course providers often claim.”
This is certainly something to think about!
Categories: Uncategorized | Comments (0) | PermalinkEnamored with Day Trading? (Part 1)
Posted by Mark on March 2, 2020 at 10:34 | Last modified: May 4, 2020 11:19The next two posts are an absolute must-read if you have any interest in day trading for a living (second-to-last paragraph).
As I have discussed many times, data is the financial industry is frequently absent. This blog mini-series focused on the lack of performance reporting. This post focused on the lack of evidence to support technical analysis.
Now we have some actual data!
Today’s post is based on “Day Trading for a Living”: an August 2019 article by Fernando Chague, Rodrigo De-Losso, and Bruno Cara Giovannetti out of the University of São Paolo in Brazil. I encourage you to take a look at the full manuscript.
Chague et al. talk about the lack of quality data about the odds faced by people who choose to try their hand at full-time day trading. The few studies that exist do not focus on individuals who trade regularly, which “largely overstimates the odds” of having success. Second, the few studies that exist do not follow individuals from their first trade, which makes it difficult to understand whether learning is possible in this domain. Finally, the few studies that do exist sample periods that predate the modern-day trading landscape, which includes “fierce competition of algorithms and high-frequency traders.”
Futures trading in Brazil is very popular. Chague et al. cite a 2018 report from the Futures Industry Association stating annual volume of the mini-Ibovespa futures totaled 706 million contracts: much greater than the E-mini S&P 500 Futures (445 million contracts) and S&P 500 Index Options (371 million contracts). Futures and options trading volume of the Brazilian Exchange ranked third worldwide (2.57 billion contracts). The population of Brazil is approximately 40% that of the USA.
This is basically to say that day trading in Brazil is virtually a national pastime—much more popular than in the United States.
The Brazilian futures industry is similar to the USA. On one [large] side of the spectrum are the social media day trading “gurus,” vendors selling day trading systems, and lots of [supposedly?] profitable indicators/newsletters for sale. These are entities that have been presumably advertising and profiting throughout the industry for years. On the other [tiny] end of the spectrum are economists, social scientists, and data scientists.
Remember this excerpt?
> The oft-quoted statistic that 90% fail within five [1-2?]
> years supports this. I don’t know who [if?] did the original
> study but it is consistent with what I’ve seen of human
> nature from attending trading groups.
The time has finally arrived to see how this shakes out by putting some actual context behind it.
Categories: Uncategorized | Comments (0) | PermalinkBlack Swan Trading Systems
Posted by Mark on February 27, 2020 at 07:02 | Last modified: May 8, 2020 11:03I have been going through my “drafts” folder this year trying to get more organized by finishing partially-written blog posts. Discussion in this post led to my thoughts on this from Sep 2018.
—————————
For me personally, I think the small sample size is still a
problem and it may be the reason why I’d be skeptical
that any statistically valid Black Swan system could
really be developed.
Ultimately, how could such a system ever be said to be
better than luck? Even if it hits the next one, two, or
three market crashes (over how many years or decades
would that take?), the sample size is still very small.
I think this is why I personally have never endeavored
to pursue development of such a system. This would also
be the root of my skepticism if I ever saw one.
I would offer up the caveat that from a practical
standpoint, hitting big on even one market crash could
make a boatload of money regardless of whether lucky
or not. I’m definitely not saying it’s a wasteful
pursuit: only one incapable of statistical validation.
Rather than developing such a directional system, I
wonder about having some long put insurance on
at all times. The insurance will lose a small amount
most of the time. Rarely, the insurance will pay
off big. Even if the total return is negative, lowering
the max drawdown of bullish strategies may still make
it a worthwhile addition (demonstrating this through
backtesting would probably face the same challenges
that I mentioned above, though). In addition, I could
always advertise “if the market goes to zero, the
system will profit handsomely.”
Musings on Naked Puts in Retirement Accounts (Part 5)
Posted by Mark on February 24, 2020 at 06:20 | Last modified: May 8, 2020 09:15I’ve been going through my “drafts” folder this year trying to finish partially-written blog posts and get more organized. The four-part mini-series ending with this post was an excellent discussion about naked puts (NP) versus vertical spreads with regard to leverage and volatility of returns. As I have said before [and I especially mean it this time], in the longshot case that someone out there could possibly benefit, what follows is Part 5 from August 4, 2017.
—————————
If I were paying someone to manage my money, then I would rather less of my capital be traded with a high degree of leverage. This is synthetically equivalent to more capital being traded with much of it in cash except I would not be paying a management fee on idle cash. [1]
One future direction for research is how standard deviation of returns and max drawdown compare to NPs from a gross dollar perspective if I lever up with vertical spreads. Given that employment of leverage will significantly decrease notional risk, what would be the comparable position size?
I suspect research cannot answer the question of proper position size to use because we never know when/if that large market crash will occur and the number of historical occurrences of said “large market crashes” is too small (see third paragraph here) for future indication.
Spreads are also harder to trade than single options so I might lose something additional to transaction fees. If I were just counting on the long option to protect from catastrophic loss, though, then that really doesn’t matter and the only question would be when to close it, which I briefly discussed in the fifth paragraph here.
—————————
I no longer agree with [1] for a couple reasons.
Most investment advisors (IA) would not trade retail accounts with a high degree of leverage. First, it is risky and not suitable for most investors. Second, for this reason most IAs probably know very little about trading with a high degree of leverage especially with regard to futures and options. Sticking with more conventional, existing products, leveraged ETFs exist but are only recommended in narrow circumstances. Again, I’m guessing it would be difficult to find IAs with expertise in this area.
Finally, trading in a leveraged manner may require cash to be left in the brokerage account unless one plans to actually take out a margin loan and pay margin interest. The one thing I know for certain in this scenario is that headwinds are against me. For this reason, I cannot recommend it.
Categories: Financial Literacy | Comments (0) | PermalinkOption Fanatic, RIA (Appendix C)
Posted by Mark on February 10, 2020 at 13:41 | Last modified: May 6, 2020 07:10Today I will finish tying up the loose ends from this blog mini-series.
I left off discussing compliance for investment advisers (IA).
What limited information I have been able to obtain about standard guidelines implemented by compliance firms has left me somewhat dazed and confused. The red tape certainly does hinder/prevent action. I don’t think it’s all for naught though. With all the chicanery that has run rampant throughout the financial industry (see fourth paragraph here), prospective investors need to be protected.
Should I go forward with my own IA, I will probably hire a lawyer and/or compliance firm that specializes in these matters. I want to trade and study trading-related matters rather than getting stuck in all the red tape.
Should I go forward with my own IA, I may consider pursuit of a relevant credential. My doctorate is in pharmacy, which is not relevant. I don’t have a CFP, a CFA, or even an MBA. I don’t believe the credentials mean much with regard to character (honesty). Nevertheless, they are a symbol of expertise and they may be good for marketing. I would have to get licensed through the Financial Industry Regulatory Authority (FINRA), however, by passing the Series 7 and/or Series 65 exams.
Why would people want me to manage their money?
Don’t pick me because I’m good; I don’t believe picking the right stocks or making the right trades is even a thing. All I can do is put the odds in my favor, which is what what I do. From that point onward, if we lose then we lose and the possibility always exists that we will. This is a different mindset but it’s what I believe is really going on.
A better reason to pick me might have to do with my pharmacy experience. What about this:
> As a pharmacist, you trusted me with your life;
> you can certainly trust me with your money.
I truly believe this even though it may sound somewhat cheezy. I gave recommendations on medication, taught people how to use medication, and evaluated medication from time to time. If people could trust me with tasks like these—and they most certainly could—then they should also be willing to trust me with their investments.
Categories: Money Management | Comments (0) | Permalink