Weekly Iron Butterfly Backtest (Part 9)
Posted by Mark on July 9, 2013 at 05:48 | Last modified: August 5, 2013 09:03In this blog series, I’m backtesting the weekly option trade described here.
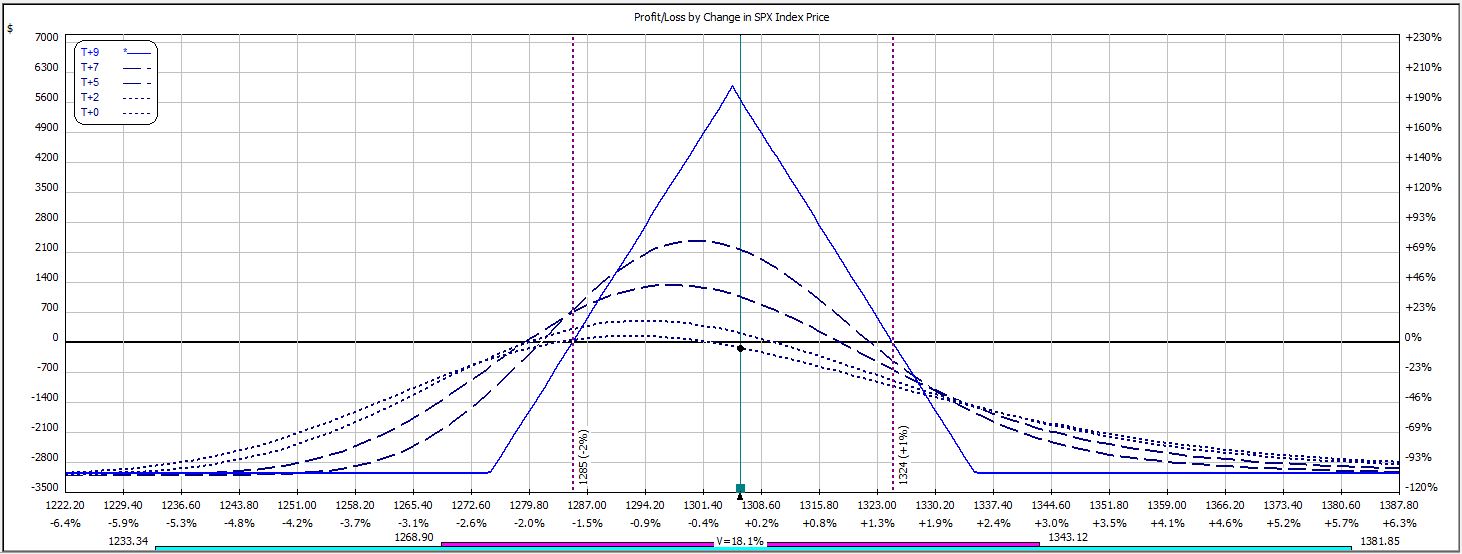
Week 8′s trade begins like this:
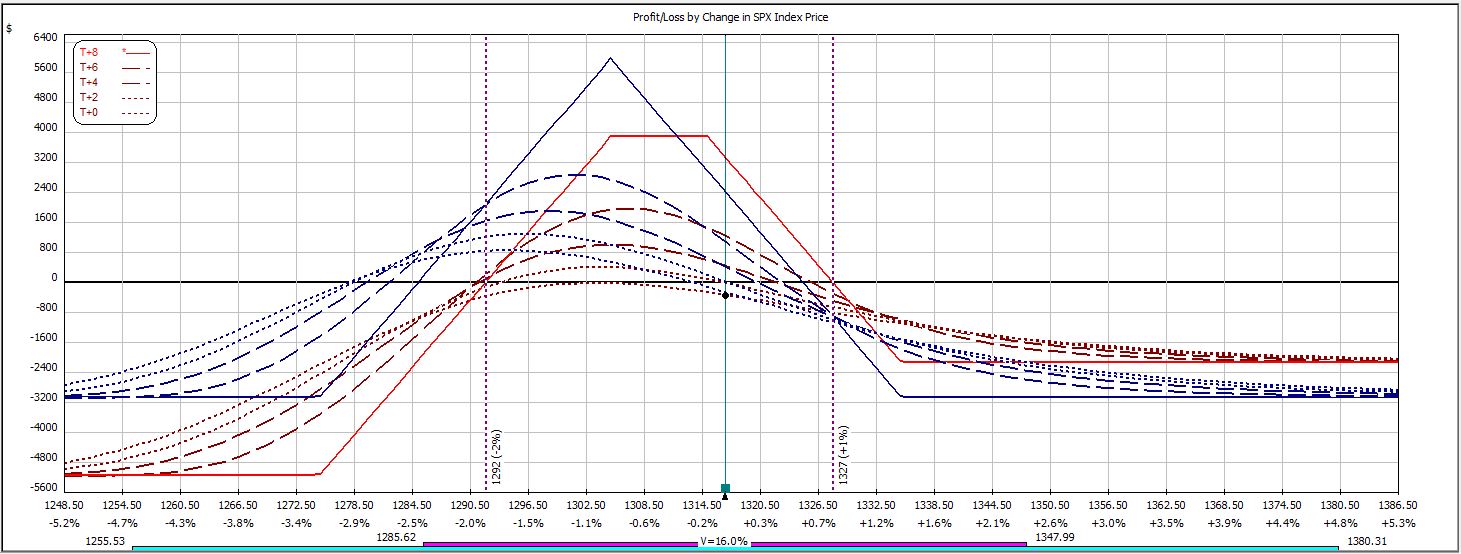
The market rallied to the first adjustment point on the next day:
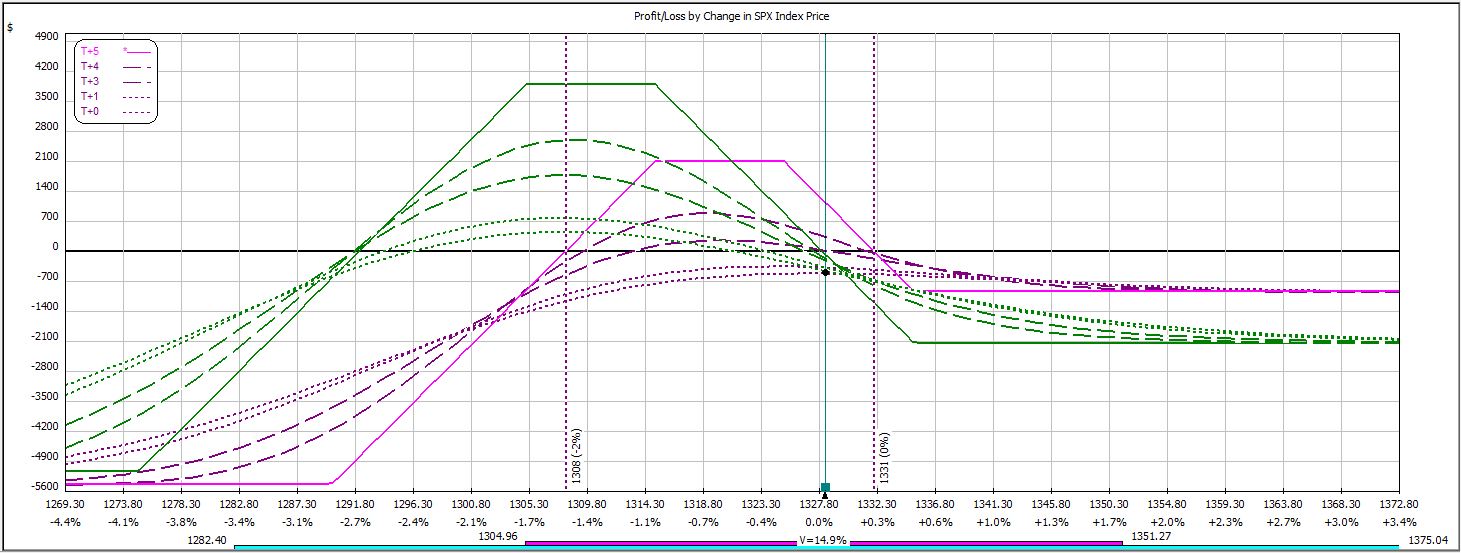
The rally continued into Monday when the second adjustment point was hit. Not only did I roll up the short calls 10 points, I also rolled the short and long put up 25 and 30 points, respectively. This adjustment, shown in pink, preserved profit potential for the trade as well as managing downside margin:
When the market pulled back on the next trading day, max loss was hit:
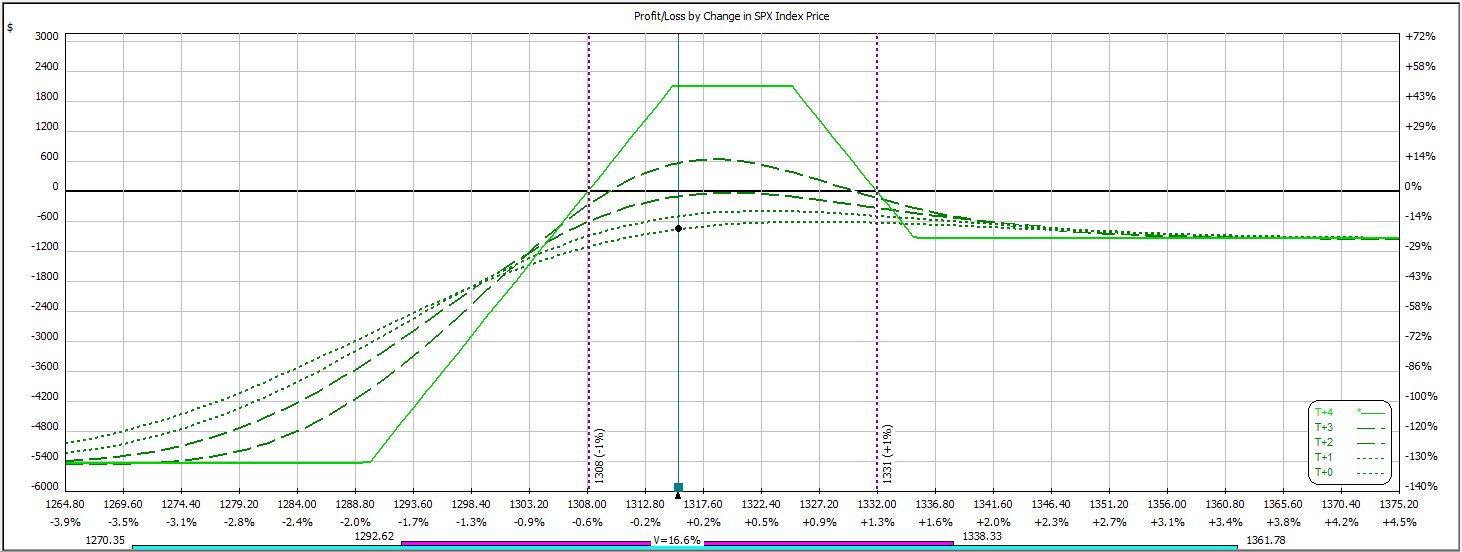
P/L on Day 1 ranged from -$285 to +$24.
P/L on Day 2 ranged from -$519 to -$345 on an adjusted margin requirement of $5,136.
P/L on Day 5 (nothing happened over the weekend) ranged from -$606 to -$537 on an adjusted margin requirement of $5,433.
Trade was closed on Day 6 for a loss of $738, which is 13.6%.
This backtested trade has now won and lost four times each.
Categories: Backtesting | Comments (0) | PermalinkWeekly Iron Butterfly Backtest (Part 8)
Posted by Mark on July 3, 2013 at 04:14 | Last modified: August 2, 2013 14:20In this blog series, I’m backtesting the weekly option trade described here.
Week 7’s trade begins like this:
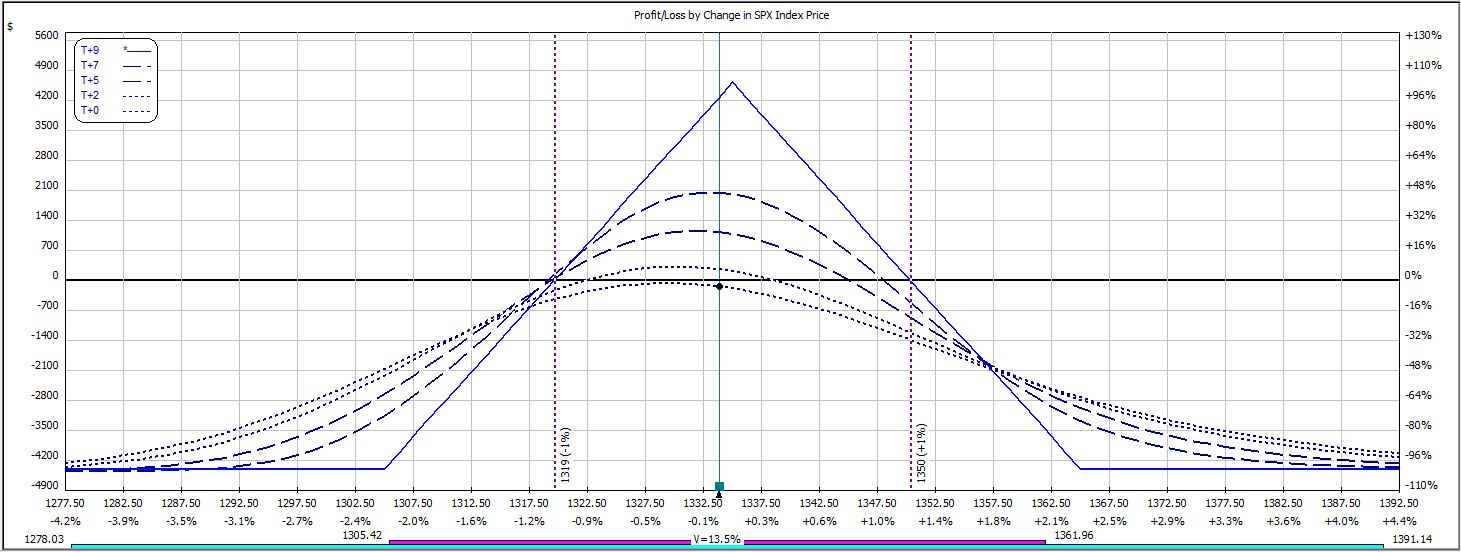
The trade closed just before the market sold off markedly:
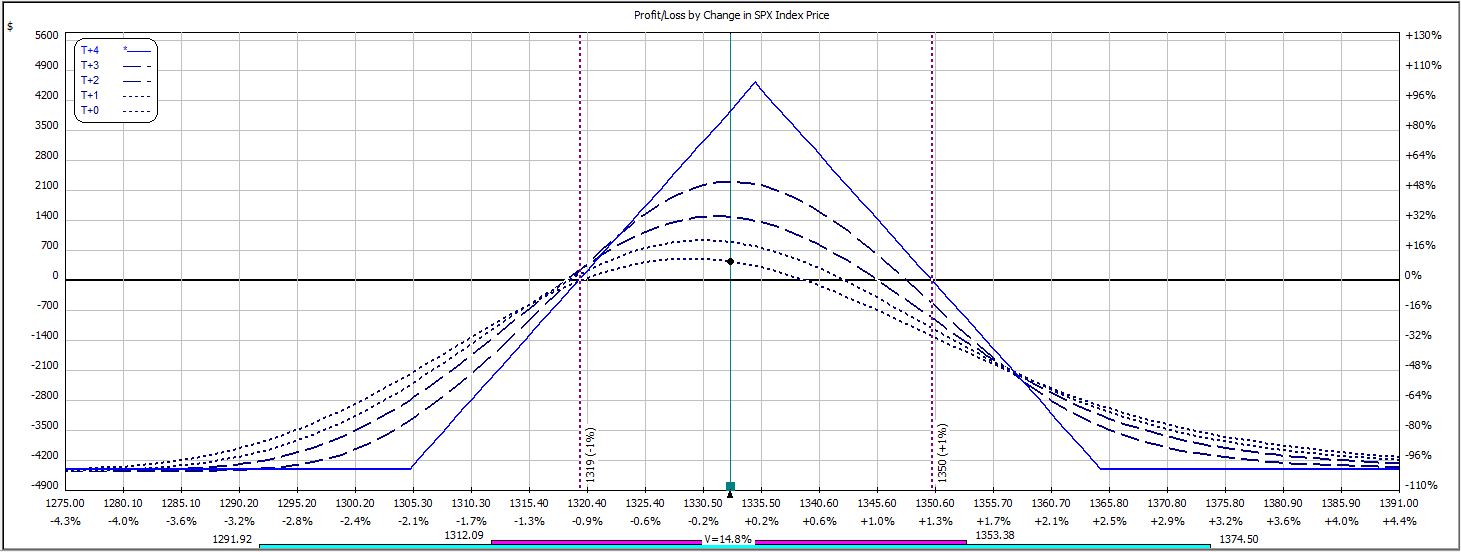
P/L on Day 1 ranged from -$399 to -$114.
P/L on Day 2 ranged from -$75 to +$318.
Trade closed on Day 5 (nothing happened over the weekend) for a profit of $444, which is 10.1% on $4,419 initial margin.
In backtesting, this trade has now won four times in seven weeks.
Categories: Backtesting | Comments (0) | PermalinkWeekly Iron Butterfly Backtest (Part 7)
Posted by Mark on July 1, 2013 at 10:40 | Last modified: August 2, 2013 10:52In this blog series, I’m backtesting the weekly option trade described here.
At inception on Week #6, the trade looked like this:
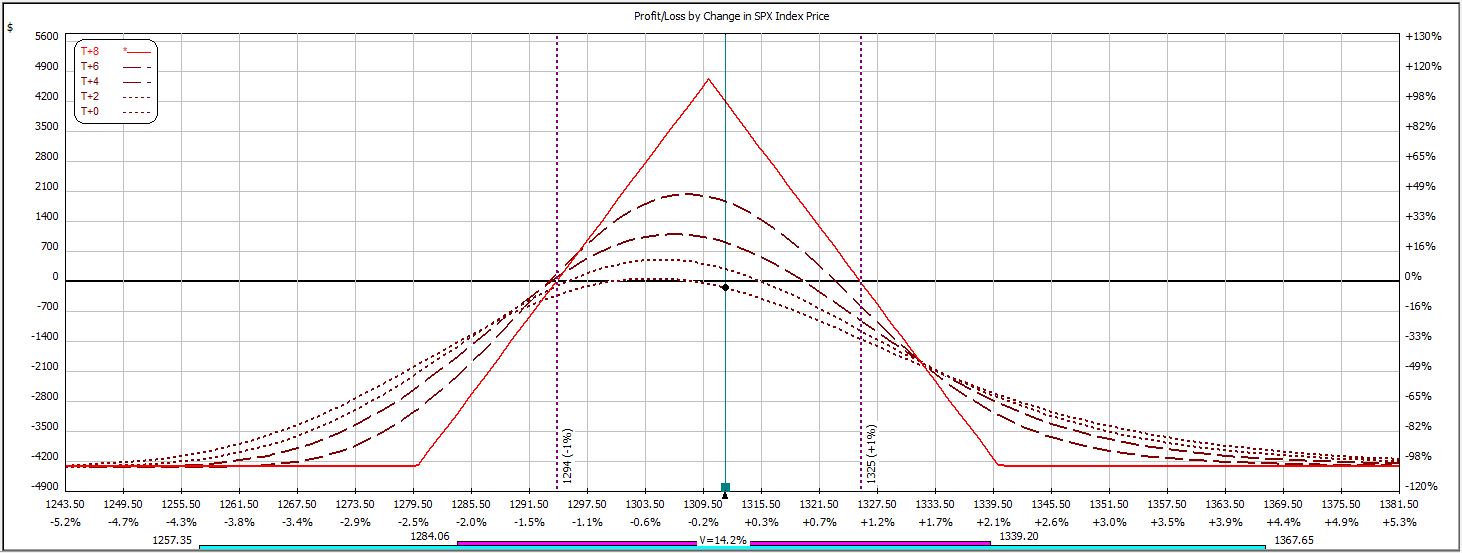
The P/L ranged from -$144 to -$837 on this day.
On Day #2, max loss was hit:
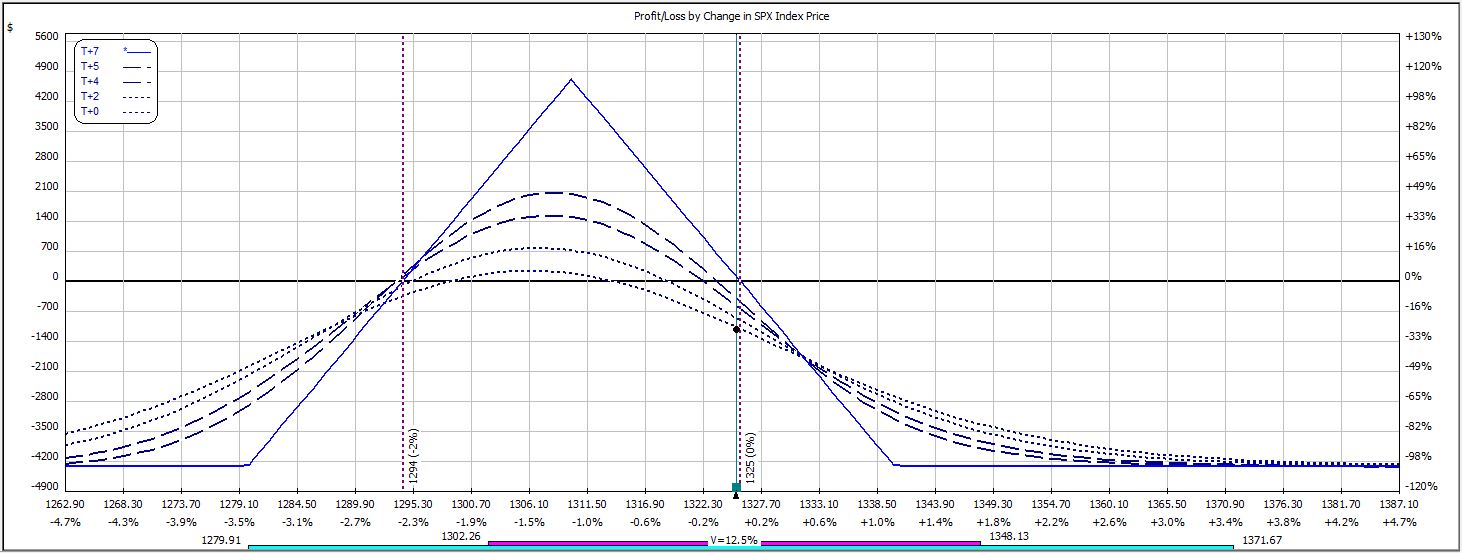
The market only had to rally 14 points to force a 26% loss on the initial margin of $4,311.
In the first six weeks of this backtest, we have seen three wins and three losses. That only tells half the story, however. The average win has been $515 versus an average loss of $1,032. That, my friends, is a recipe for disaster!
Time will tell whether these early tendencies persist.
Categories: Backtesting | Comments (0) | PermalinkWeekly Iron Butterfly Backtest (Part 6)
Posted by Mark on June 28, 2013 at 04:16 | Last modified: August 2, 2013 10:37In this blog series, I’m backtesting the weekly option trade described here.
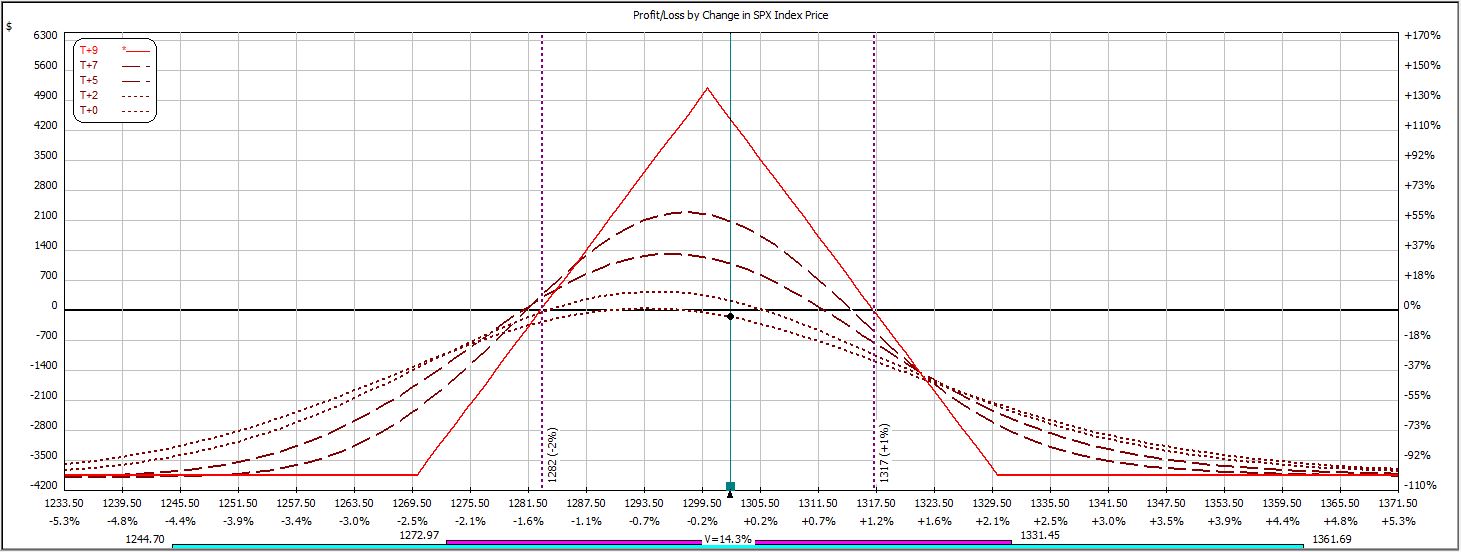
Week #5 is a loser. At inception, the trade looked like this:
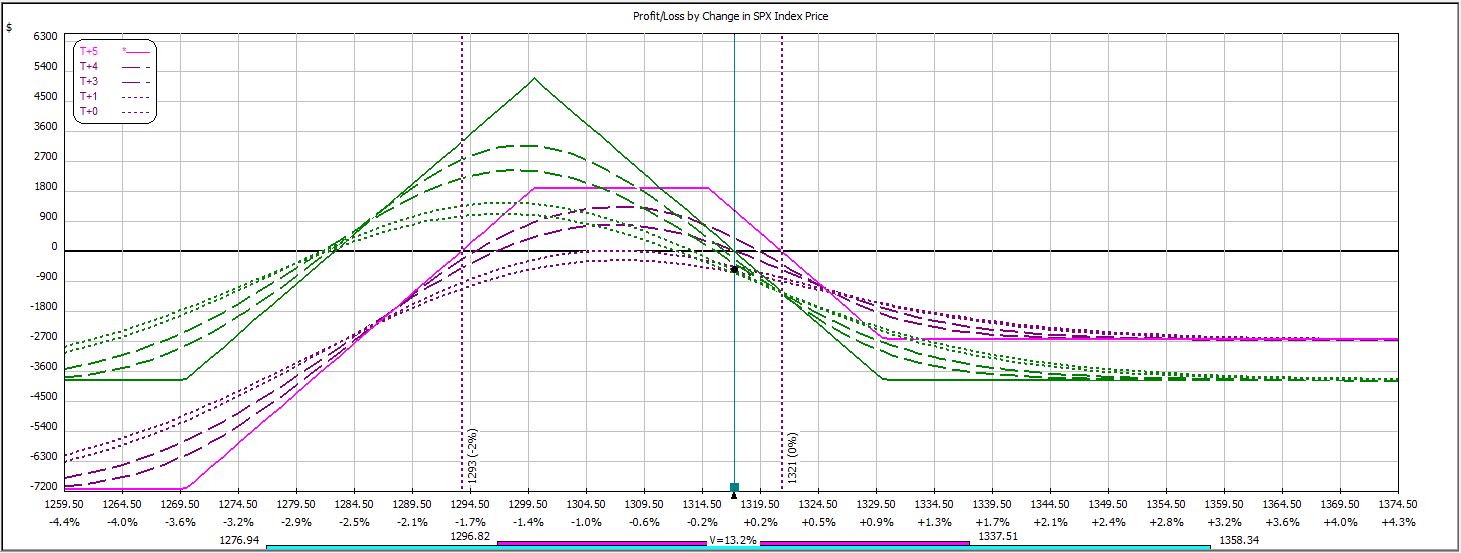
The market rallied 15 points to force an adjustment on Day #5. Shown in purple, I rolled the short calls up:
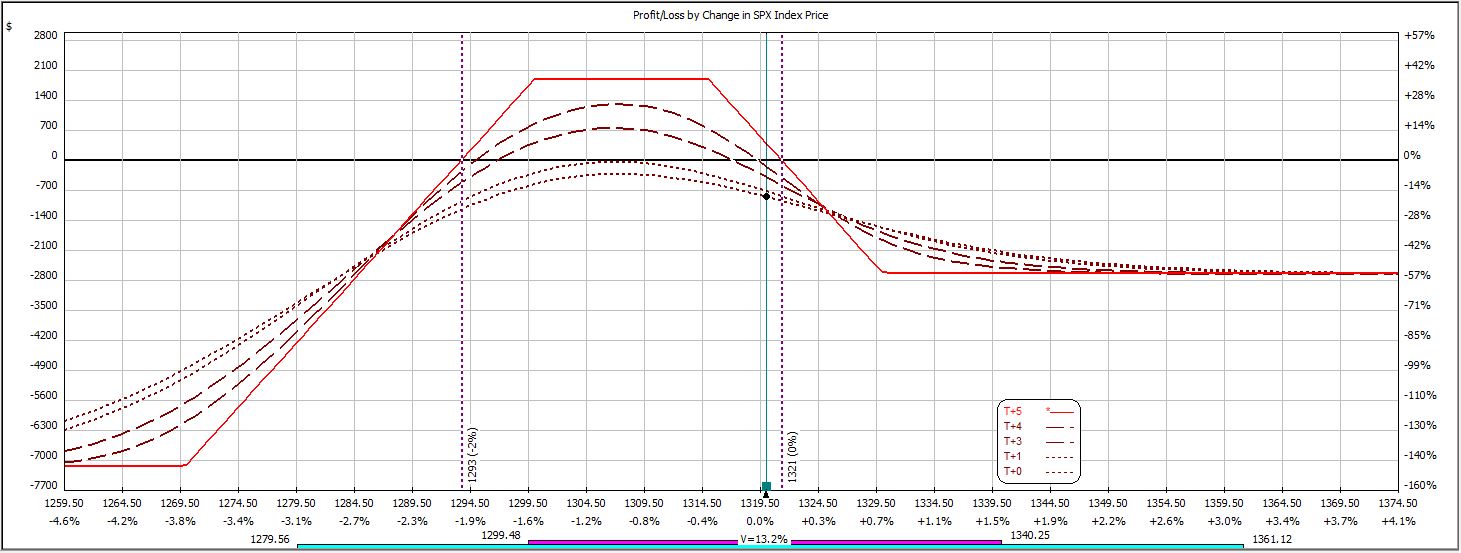
As the uptrend continued, max loss was hit soon after:
P/L on Day #1 ranged from -$177 to +$87 on $3,858 margin requirement for three contracts.
P/L on Day #2 ranged from -$90 to +$264.
P/L on Day #5 (nothing happened over the weekend) ranged from -$582 to -$837 (max loss), which is a loss of 11.7% on an adjusted margin requirement of $7,137.
In back-to-back weeks I have now seen sharp whippiness and strong trending cause this trade to lose. The win-loss record stands at 3-2.
Categories: Backtesting | Comments (0) | PermalinkWeekly Iron Butterfly Backtest (Part 5)
Posted by Mark on June 26, 2013 at 05:55 | Last modified: August 1, 2013 10:21In this blog series, I’m backtesting a weekly option trade described here.
Week #4 presents the first loser of the bunch. At inception, the trade looked like this:
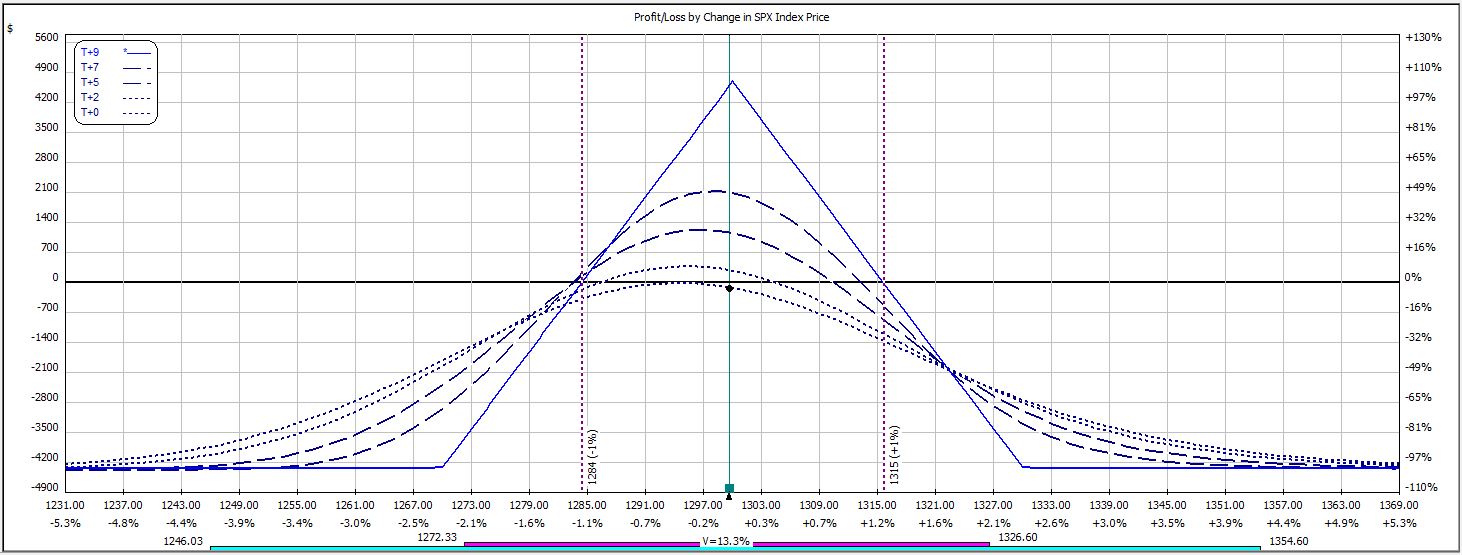
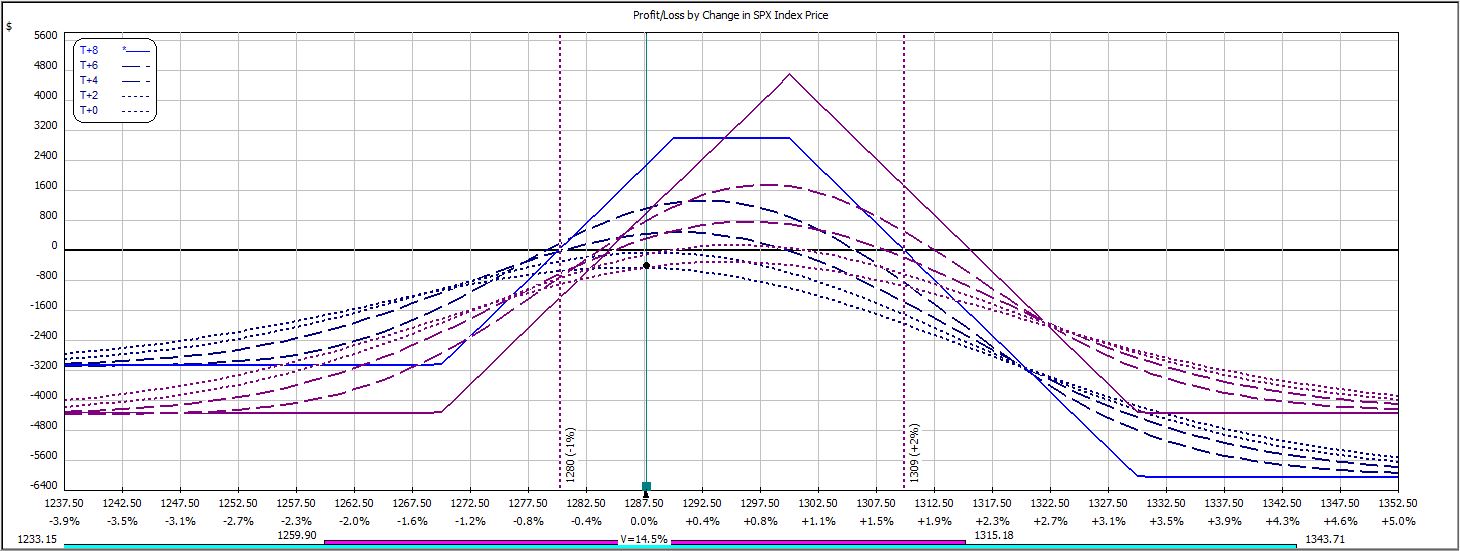
The market tanked on Day #2 forcing two adjustments. Adjustment #1 involved rolling down the short put 10 points. This is seen in blue:
Adjustment #2 involved rolling down the put spread, rolling the short call 10 points closer, and rolling the long call 15 points closer. This is seen below in green:
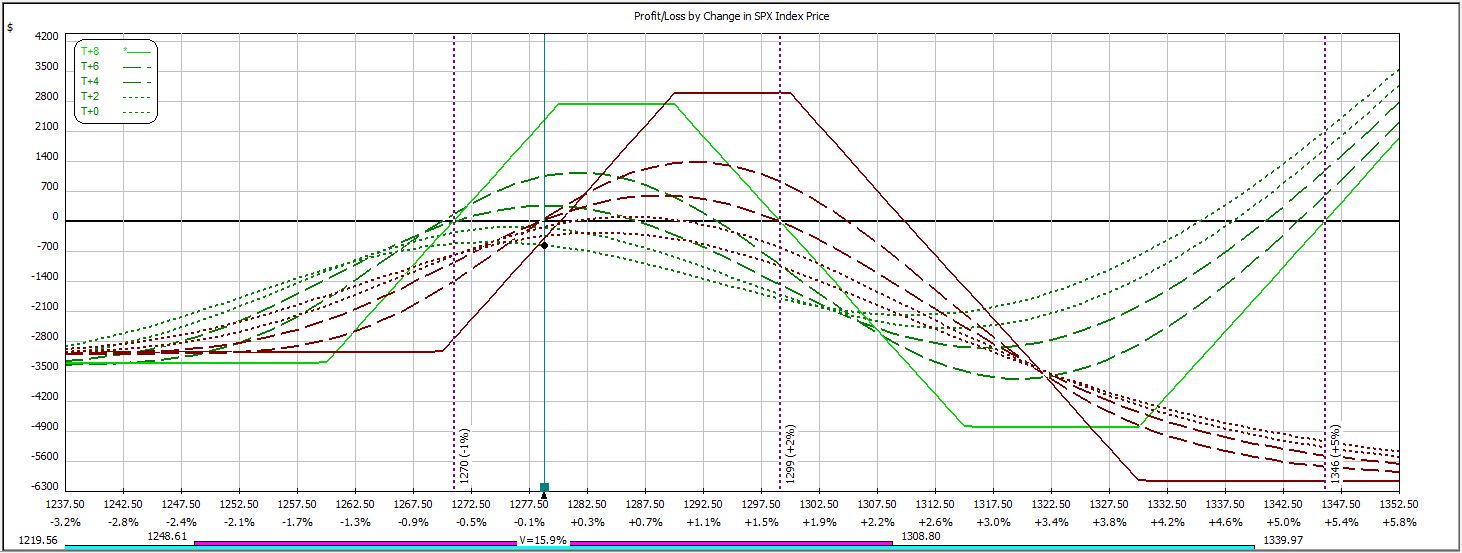
On the put side, although rolling the vertical rather than the short option alone increases downside risk, I had already cut downside risk with the previous adjustment. The net effect would leave downside risk roughly equivalent (in fact it was $3,276, which is still less than the original margin requirement).
On the call side, I rolled the short option closer to recoup some potential profit in the trade. I rolled the long option even closer to manage upside risk.
On Day #6, the market gapped higher forcing me to exit at max loss:
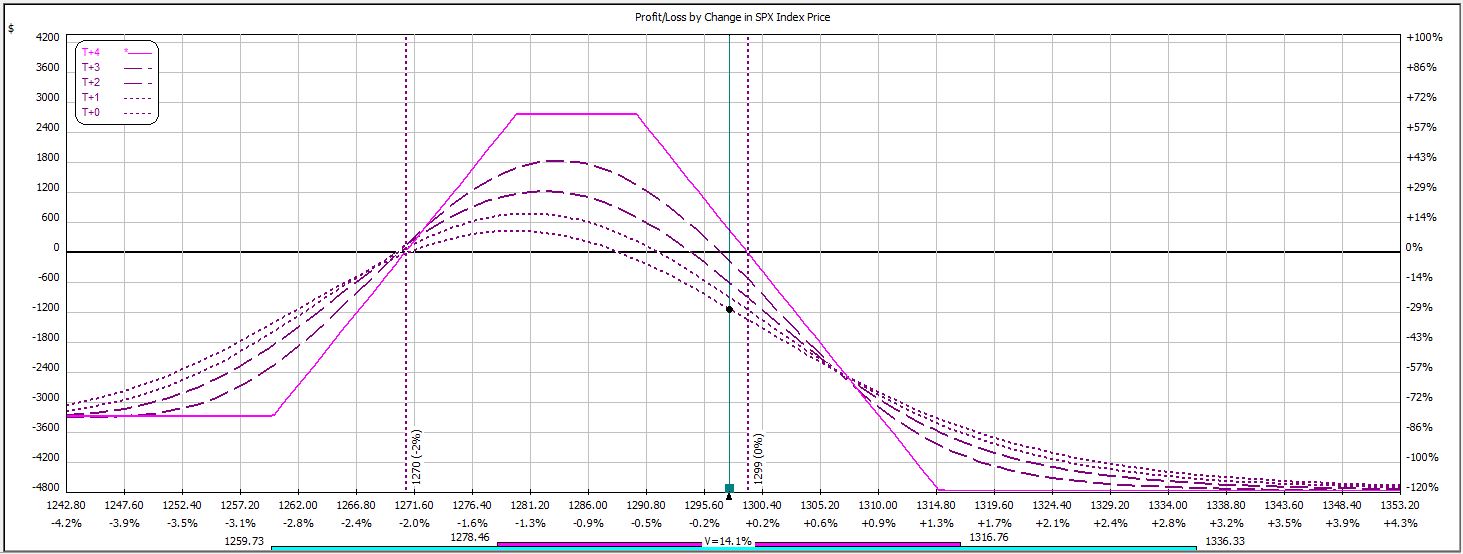
P/L on Day 1 ranged from -$387 to -$69.
P/L on Day 2 ranged from -$864 to +$102 and the margin requirement increased from $3,915 to $6,057 on three contracts.
P/L on Day 5 (nothing happened over the weekend) ranged from -$405 to -$234 on margin of $4,776.
Trade closed on Day 6 with a loss of $1,137, which is -18.8% on max margin.
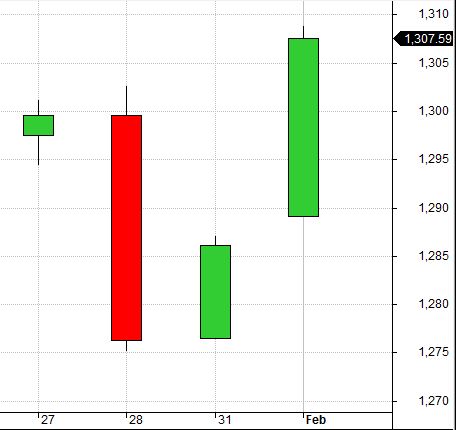
Relative to the first three weeks, the market was very whippy during the short time period. This trade will not win in the face of such price action:
The “$6M question” is whether this is the exception or the norm.
Categories: Backtesting | Comments (0) | PermalinkWeekly Iron Butterfly Backtest (Part 4)
Posted by Mark on June 24, 2013 at 07:42 | Last modified: August 1, 2013 07:57In this blog series, I’m backtesting a weekly option trade described here.
The third week required an adjustment. At inception, the trade looked like this:
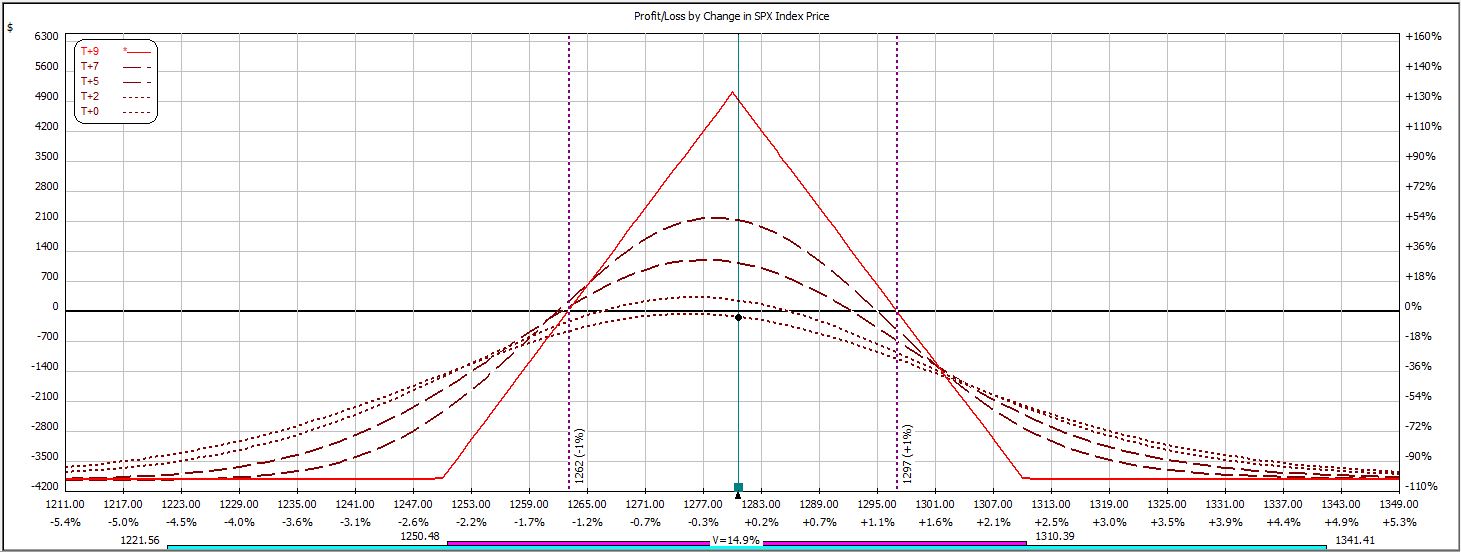
The market was 10 points higher on Day 2, which required me to roll up the short call:
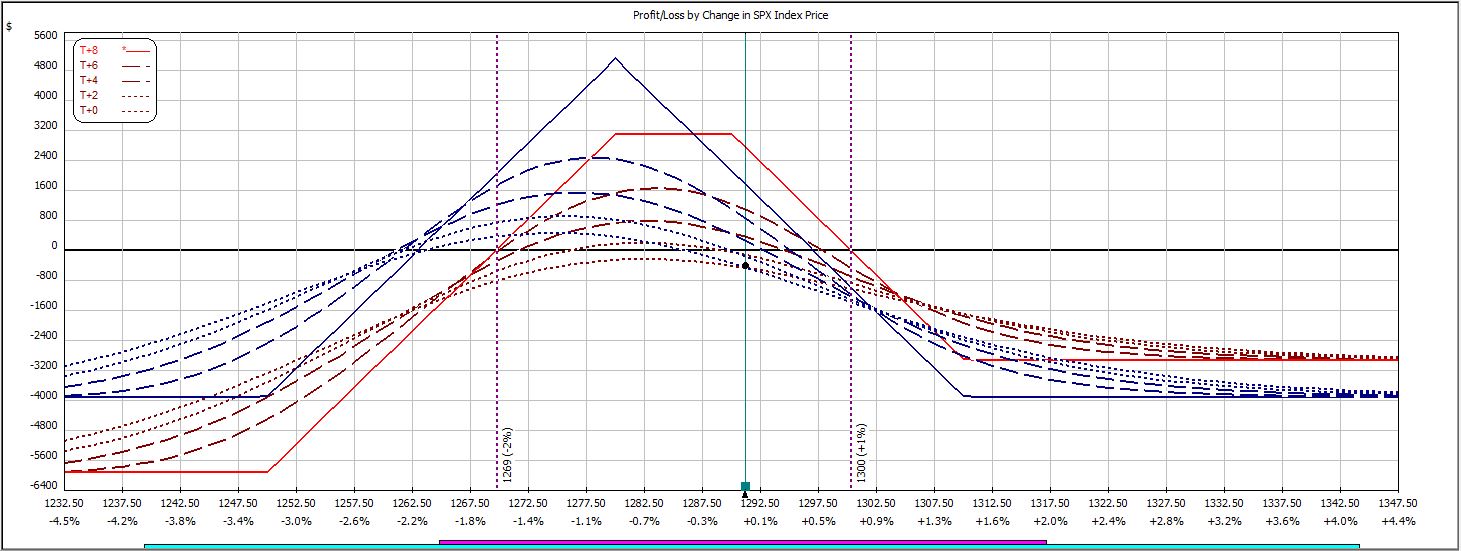
A discussion may be had whether to roll up the short call or the short call vertical spread. The former cuts net position delta while the latter does not increase risk as much. Although the former increase risk (margin requirement) more, that risk is on the profitable side of the trade. If the market continues to trend then the risk is actually less. This may be seen in the above graph that shows the adjusted trade superimposed on the original trade.
Which adjustment is better? That is a very difficult question to answer that would require extensive backtesting. I may be able to do that eventually for now I continue one week at a time.
P/L on Day 1 ranged from -$144 to +$39.
P/L on Day 2 ranged from -$426 to +$189 and the margin requirement increased from $3,915 to $5,931 on three contracts.
P/L on Day 5 (nothing happened over the weekend) ranged from +$72 to +$216.
P/L on Day 6 ranged from $237 to $447, which is when I closed the trade:
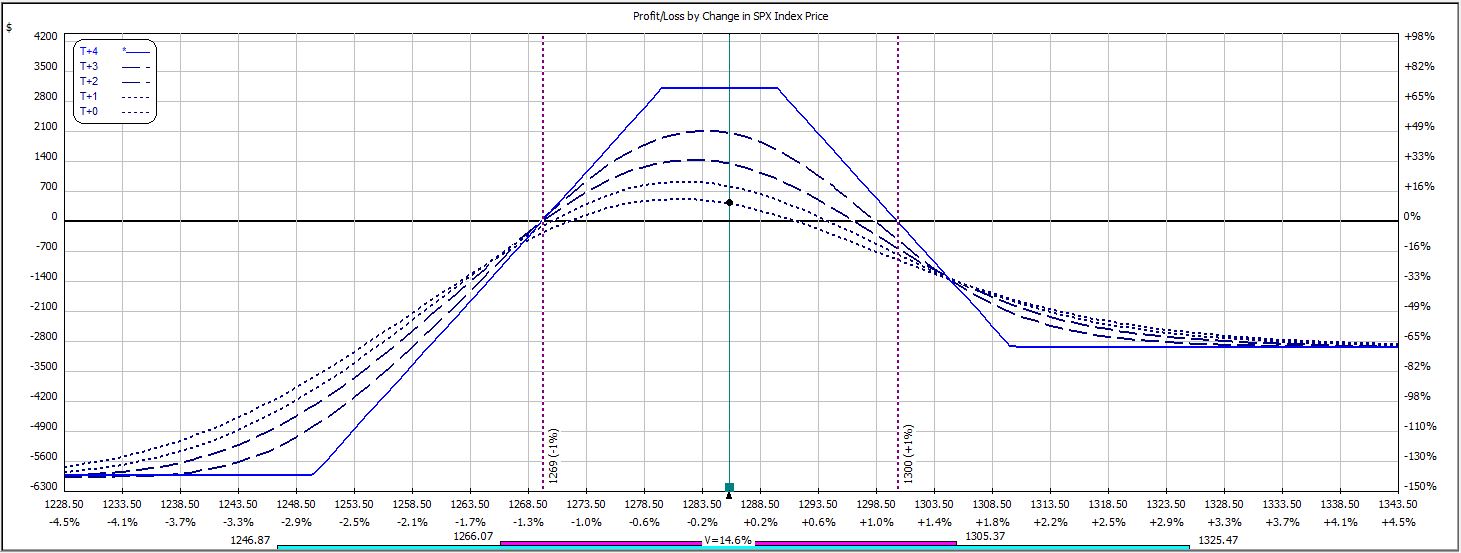
On the increased margin, return on investment was 7.5% on this trade.
Another question for debate is what to do if the market returns to its original price after rising or falling 10 points and forcing an adjustment: undo the adjustment or let it ride? This is another question that cannot be answered yet. The current trade does suggest, however, that adjustment requires staying in the trade longer to reach profit target. That makes theoretical sense.
Thus far, this trade has three wins and zero losses.
Categories: Backtesting | Comments (0) | PermalinkWeekly Iron Butterfly Backtest (Part 3)
Posted by Mark on June 21, 2013 at 07:09 | Last modified: August 1, 2013 07:40In this blog series, I’m backtesting a weekly option trade described here.
The second week was flawless. At inception, the trade looked like this:
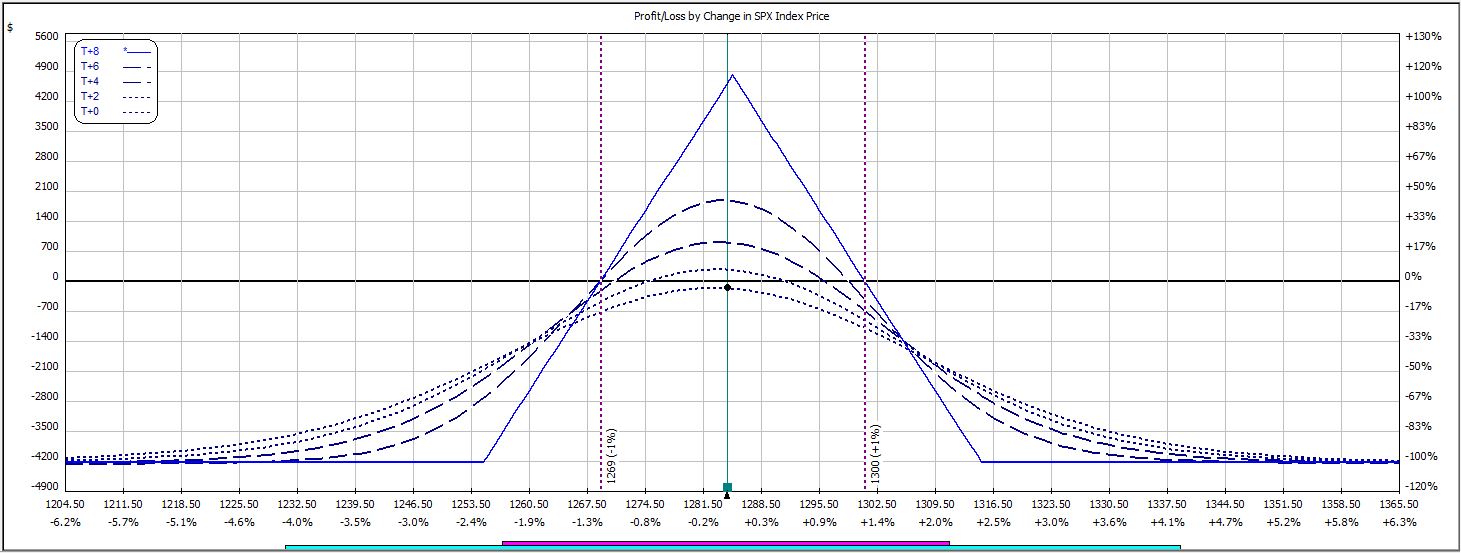
P/L on Day 1 ranged from -$114 to +$78.
P/L on Day 2 ranged from +$87 to +$324.
P/L on Day 6 (nothing happened over the weekend or on MLK day) was $570, which is when I closed the trade:
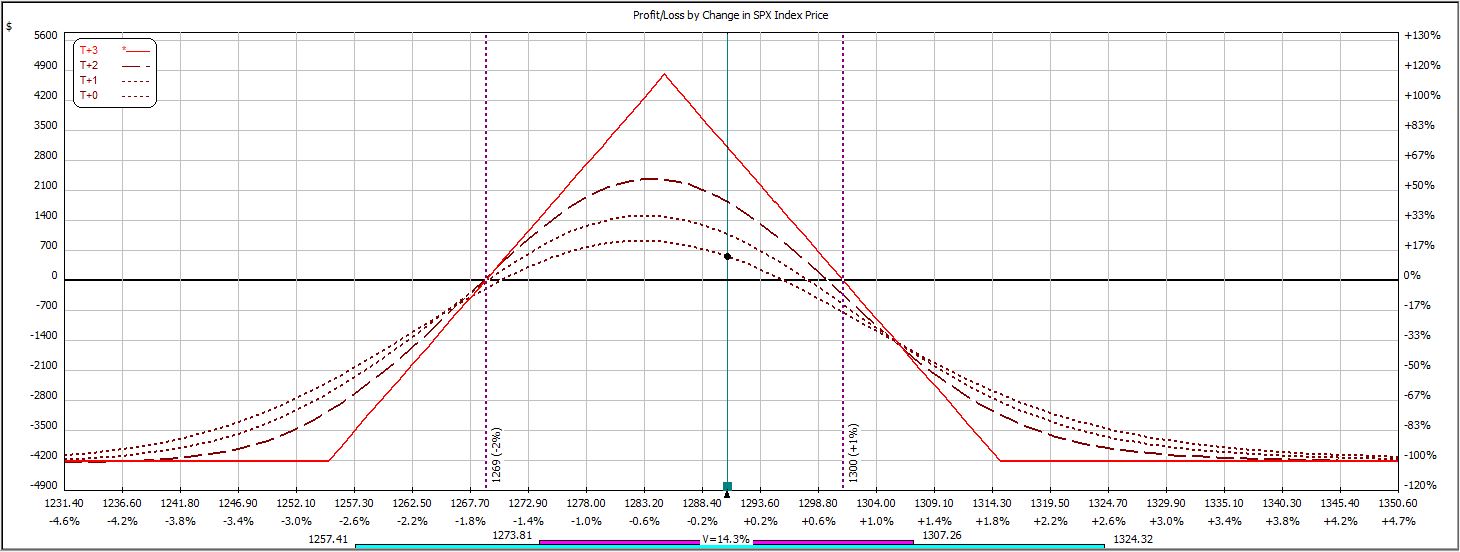
No adjustments were required for this trade.
Margin remained constant at $4,230 for three contracts. Return on investment was 13.5%.
Thus far, this trade has two wins and zero losses.
Categories: Backtesting | Comments (0) | PermalinkWeekly Iron Butterfly Backtest (Part 2)
Posted by Mark on June 19, 2013 at 06:53 | Last modified: August 1, 2013 07:40In this blog series, I’m backtesting a weekly option trade described here.
The first week was flawless. At inception, the trade looked like this:
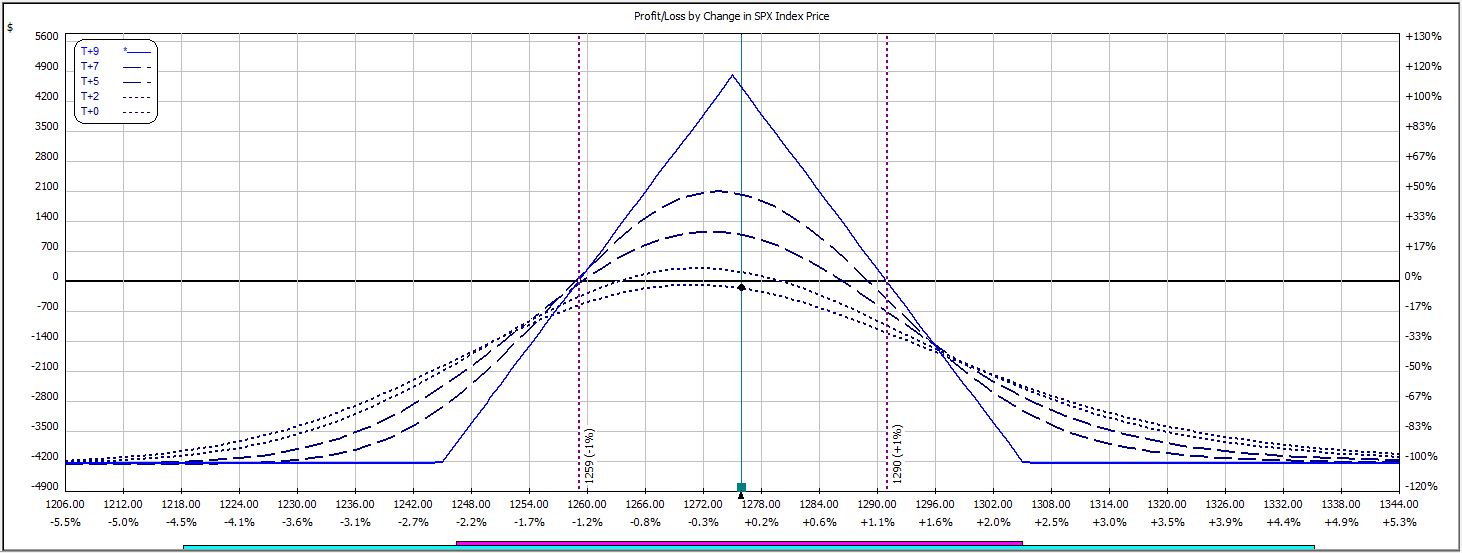
P/L on Day 1 ranged from -$237 to -$12.
P/L on Day 2 ranged from +$18 to +$333.
P/L on Day 5 (nothing happened over the weekend) ranged from +$123 to +$528. The latter included allowing the long call to expire worthless since it was listed at $0.15 upon trade close, which looked like this:
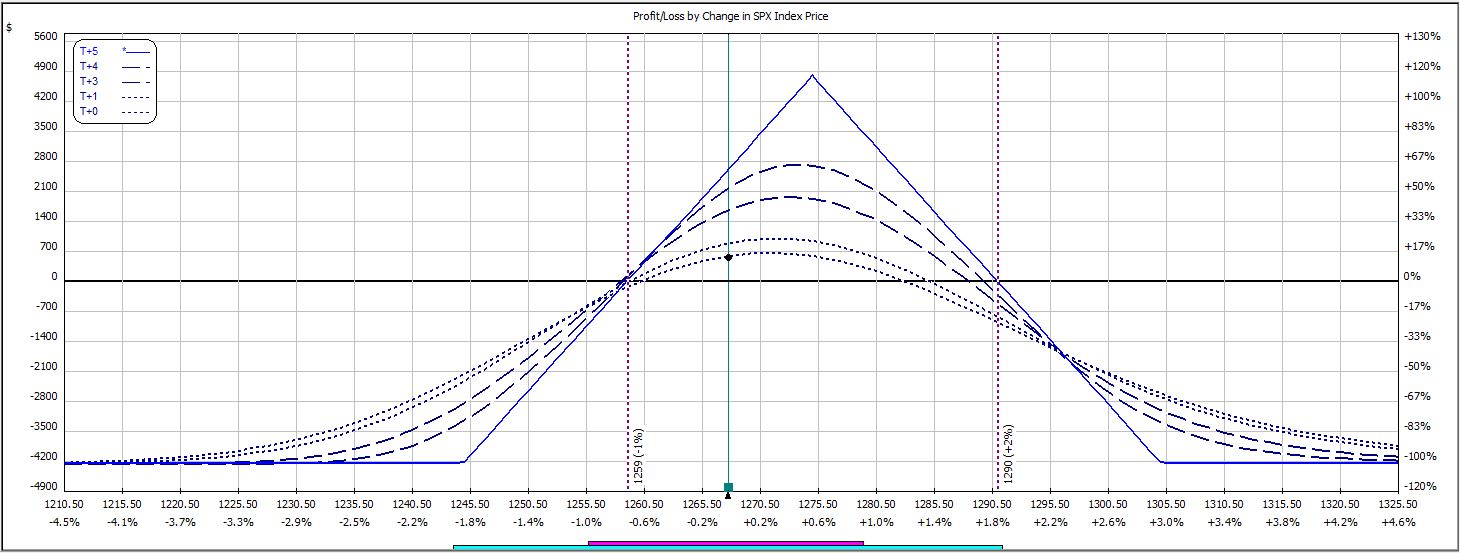
No adjustments were required for this trade. While the market was over 10 points from its starting point on Day 5, since the trade was still profitable I did not adjust.
Margin remained constant at $4,236 for three contracts. Return on investment was 12.5%.
Categories: Backtesting | Comments (0) | PermalinkWeekly Iron Butterfly Backtest (Part 1)
Posted by Mark on June 17, 2013 at 06:10 | Last modified: August 1, 2013 08:23With this post, I’m going to start backtesting a weekly iron butterfly trade. I have been hearing from a number of traders that when traded every week, this can generate an average profit of 3-5%. My skepticism reigns supreme.
My trading plan will be as follows:
–Enter trade at the money on Thursday before expiration week.
–Target 10% profit on initial capital and keep max loss at 20%.
–If market rallies 10 points from initial price then roll out distressed short option by 10 points.
–If market moves another 10 points in the same direction then repeat adjustment or roll entire spread.
–Also at second adjustment, roll profitable vertical closer to the money to manage margin requirement.
–Do not adjust if P/L is positive.
–Assess transaction costs of $6/contract.
Hopefully I will be out of most trades by Monday or Tuesday of expiration week.
I have backtested this before using $16/contract transaction fees and gotten terrible results. I realize $16/contract is harsh. When it comes to transaction costs in backtesting though, I usually spare no potential expense because this is a great way to make a trade seem more profitable than it really can be.
As I said, I’ve heard a number of other traders say this works.
Traders lie.
Could I be missing out on a good thing by being too skeptical?
Here’s to second chances!
Categories: Backtesting | Comments (1) | PermalinkThe “Fitz” of Retrospect (Part 2)
Posted by Mark on June 11, 2013 at 04:12 | Last modified: July 25, 2013 12:31In my last post, I discussed an MTZ trade that Dan Fitzpatrick explained could have easily made you 10% in a short period of time. Upon closer scrutiny this trade seems to be more difficult than promised, no thanks to the illusion of Retrospect.
Fitzpatrick said you could buy on a move above the thick black line and ride the stock to victory:
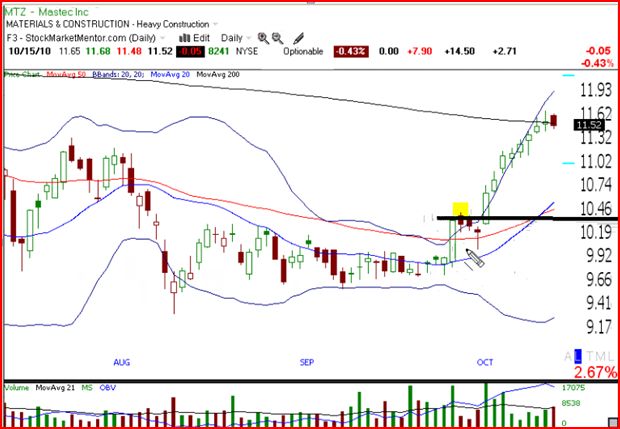
A closer look reveals that MTZ definitely traded higher the next day:
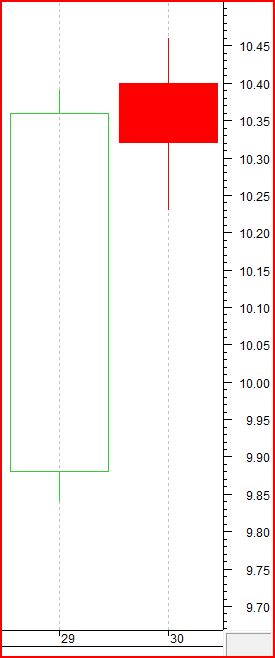
MTZ closed at $10.36 on the 29th and opened at $10.40 on the 30th. MTZ then traded up to $10.46: a full 1% above the previous close. While Fitz suggests this day to be weak and not reason to buy, nothing weak is evident in the first 30 minutes when the stock opened higher and continued higher.
If I were to truly follow Fitz’s directions then I would have had a more difficult trade than Fitz represents. The easy way to follow Fitz’s lead would be to set a buy-stop to enter long above $10.36. Two days later, MTZ traded down to $10.04 intraday: a loss of 3.1%. This would have undercut the 50-day moving average (seen on the top chart) and caused some people to exit at a loss. If I would enter on a buy-stop intraday then why wouldn’t I exit on an intraday stop-loss?
Retrospect is the illusion that masks the difference between what Dan Fitzpatrick says would happen with this trade and what really would have happened. Getting on-board and riding the stock up 10%+ is the fairy tale we want to believe. The difference between that and the reality of buying, losing 3.1%, and then riding onto victory was significant for those who didn’t stick around to be rewarded with the profits!
Application of Retrospect means trading away from a chart’s hard right edge, which is not reality. The illusion of Retrospect therefore allows one to gloss over particular details that involve a great deal of endless debate, instruction, and theory. This is what makes trading so difficult to learn and to master.
Categories: optionScam.com | Comments (0) | Permalink